Reporte de Color 2020 de BASF: Una gama más amplia de colores salió de las líneas de ensamble del mundo en 2020

– Ampliando los espacios de color, hacen que el espectro general sea más amplio que en 2019.

– Tonalidades diversas de azul, rojo, amarillo y violeta avanzan en algunas regiones.

– A pesar del cambio en los colores, el blanco, negro, plata y gris siguen un patrón conocido, cubriendo la mayoría de los vehículos producidos.

CIUDAD DE MEXICO, 7 de enero de 2021 /PRNewswire/ — El Reporte de Color 2020 de BASF para Coatings de Automóviles OEM muestra que la paleta de color para automóviles está dando un giro en formas no convencionales,…

– Ampliando los espacios de color, hacen que el espectro general sea más amplio que en 2019.

– Tonalidades diversas de azul, rojo, amarillo y violeta avanzan en algunas regiones.

– A pesar del cambio en los colores, el blanco, negro, plata y gris siguen un patrón conocido, cubriendo la mayoría de los vehículos producidos.

CIUDAD DE MEXICO, 7 de enero de 2021 /PRNewswire/ — El Reporte de Color 2020 de BASF para Coatings de Automóviles OEM muestra que la paleta de color para automóviles está dando un giro en formas no convencionales, revelando una amplia gama de colores cromáticos que llegarán a las líneas de ensamble a nivel mundial.

Color de automóvil “Dark Seltzer” de BASF

Diversas tonalidades como azul y amarillo van avanzando en algunas regiones, mientras que el rojo y violeta van acercándose al primer lugar que tienen los colores acromáticos en otras partes del mundo. Los espacios de color que van creciendo ampliaron el espectro general con respecto a 2019 y agregaron una chispa de brillo.

A pesar del cambio en los colores, los colores acromáticos (blanco, negro, plata y gris) siguieron un patrón conocido, cubriendo la mayoría de los vehículos producidos. Como ha ocurrido durante varios años, el blanco sigue siendo el color de automóviles más popular en todo el mundo. Tiene una belleza clásica, atemporal, y una conexión tanto al ambiente como a la alta tecnología.

La información citada en el reporte muestra una producción total de vehículos menor que la de años pasados. Incluye tiempos en que los fabricantes de automóviles tuvieron que cerrar debido al COVID-19. La pandemia global ha afectado profundamente la economía de la movilidad y el mundo.

EMEA: Mayor diversidad de colores y tonos cromáticos
Europa, Medio Oriente y África (EMEA) sigue la tendencia global de colores cromáticos. En 2020, alrededor del 11% de los vehículos nuevos en EMEA estuvieron pintados de azul, haciéndolo el color cromático más popular. El violeta es un nuevo entrante en el mercado, aumentando aún más la diversidad. Otros colores cromáticos también van ganando popularidad, especialmente en SUVs más pequeñas, al crecer su segmento de mercado.

Parte de la variedad viene de la diversidad de tonos. En EMEA, los fabricantes de vehículos de OEM usaron más de 160 tonos distintos de azul en 2020 en vehículos. El gris ocupa el segundo lugar con 140 tonos. Ambos espacios de color fueron más diversos que el blanco, que solamente tuvo 70 tonos distintos.

En el espectro acromático, el blanco sigue predominando con 28% del mercado, seguido del gris y el negro.

«La variedad de colores cambia con el tamaño. Por ejemplo, si bien el violeta tiene un lugar único en las SUVs de tamaño mediano, no aparece en grandes cantidades en SUVs pequeñas o más grandes,» señaló Mark Gutjahr, director de Diseño de Color Automotriz, EMEA. «Lo opuesto ocurre con el amarillo, que aparece en los muy pequeños y los muy grandes, pero no en los medianos. Estas son posiciones de color específicas y únicas que aparecen y desaparecen en los segmentos.»        

Norteamérica: Más azul, tal como anticipamos
Los compradores de automóviles en Norteamérica tuvieron menos elecciones para los colores cromáticos, pero esto no significa que estén eligiendo menos automóviles, camiones o SUVs cromáticos. El azul ganó más popularidad como color para automóviles en Norteamérica , desplazando al rojo, mientras que el beige y el café salieron de la lista. Esto deja al verde como el único otro color cromático con números significativos en la región.

Los tonos de azul se perciben como más elegantes, y parece que los compradores que en el pasado han elegido el beige se están moviendo hacia los azules o los grises. Los diseñadores de BASF fueron capaces de anticipar esto. Desde 2016, los diseñadores de BASF describieron el azul como «una dirección principal de color para la industria automotriz, la cual ganará participación de mercado en los años siguientes.» Con frecuencia, los diseñadores de automóviles ven los modelos con 3-4 años de anticipación al desarrollar colores, y el mercado ha resultado exactamente como lo predijeron.

«Hay mucho por lo que emocionarse acerca de los colores brillantes que estamos viendo,» señaló Paul Czornij, director de Diseño, Américas. «Tal como predijimos hace tres o cuatro años, el azul está teniendo un momento bajo el sol, y estamos usando algunos efectos y pigmentos muy hermosos que aumentan las posibilidades del tono y la textura en este importante espacio de diseño.»

Asia Pacífico: Surgen el negro y el gris, al tiempo que aparecen colores más brillantes
En Asia Pacífico se ubica el volumen más elevado de producción automotriz del mundo, y constituye un microcosmo en la popularidad del color a nivel global. Si bien cada región es diferente, las preferencias en Asia Pacífico coinciden con los datos a nivel global, y sus colores brillantes reflejan el despertar que están teniendo los colores cromáticos en todos lados.

El blanco sigue siendo el color más popular en la región, cubriendo cerca del 48% de los vehículos producidos. El negro y el gris continúan aumentando, siguiendo una tendencia a tres años para dejar atrás el predominio del blanco.

Si bien los números totales no son enormes, el café, verde y violeta son todos consistentes en popularidad de color. Va a pasar mucho tiempo antes de que compitan con el blanco como el más popular, pero por ahora, se suman a la tremenda diversidad de color en Asia Pacífico.

«La gente en Asia Pacífico realmente disfruta eligiendo el color de sus vehículos. Los colores están muy orientados a la humanidad, flexibles y libres, mostrando la diversidad de la región y su gente,» señaló Chiharu Matsuhara, director de Diseño, Asia Pacífico.

Sudamérica: Los compradores conservadores eligen colores más conservadores
Los colores como el rojo y el azul, que son tan populares en otras regiones del planeta, siguen siendo jugadores en Sudamérica, especialmente entre compradores de automóviles que están intentando expresar su individualidad con autos más deportivos. Lo más significativo es el amor del mercado por los colores acromáticos.

Históricamente, los compradores de automóviles en Sudamérica han elegido colores más tradicionales, menos llamativos. Como en otras regiones, el blanco es, por mucho, el favorito, cubriendo cerca del 39% de los vehículos OEM. La popularidad del gris y del plata es mayor que en otras regiones, con 18% para cada uno. El negro tiene la menor preferencia entre los colores acromáticos, con 12%. En conjunto, los colores acromáticos representan una participación de 87%.

A diferencia de otras regiones, el rojo resalta como el color cromático más presente, con 9%. Diversas tonalidades de azul son importantes a nivel mundial, mientras que, en Sudamérica, el azul representa solamente 2% del mercado. El naranja es un nuevo entrante, el café se sostiene y el beige casi ha desaparecido.

«Las tendencias que son populares en otras partes del mundo se tardan en afianzar en Sudamérica. Aunque es un continente con muchos aspectos de colores en su cultura, la gente tiende a ser más conservadora con sus automóviles,» señaló Marcos Fernandes, director regional de Desarrollo de Negocios, Coatings Automotrices para Sudamérica.

El Reporte de Color 2020 de BASF para Coatings de Automóviles OEM es un análisis de datos de la división de Coatings de BASF con base en la producción automotriz y aplicación de pintura a vehículos ligeros a nivel global en 2020.

Acerca de la división de Coatings de BASF

La división de Coatings de BASF es un experto global en el desarrollo, producción y comercialización de OEM para automóviles y recubrimientos de re-terminado, pinturas decorativas, así como tratamientos innovadores y sustentables para substratos de metal, plástico y vidrio aplicados para superficies en una amplia gama de industrias. El portafolio está completado por el programa «Innovación Más Allá de la Pintura» («Innovation Beyond Paint«) que busca desarrollar nuevos mercados y negocios. Creamos soluciones avanzadas de desempeño e impulsamos el desempeño, diseño y nuevas aplicaciones para cubrir las necesidades de nuestros socios en todo el mundo. BASF comparte habilidades, conocimientos y recursos de equipos interdisciplinarios y globales para beneficio de los clientes, operando una red de colaboración de sitios en Europa, Norteamérica, Sudamérica y Asia Pacífico. En 2019, la división de Coatings obtuvo ventas globales de aproximadamente €3.75 mil millones.

Soluciones más allá de su imaginación – Coatings de BASF. Para obtener más información acerca de la división de Coatings de BASF y sus productos, visite: www.basf-coatings.com.

Acerca de BASF

En BASF, creamos química para un futuro sustentable. Combinamos el éxito económico con la protección del medio ambiente y la responsabilidad social. Más de 117,000 empleados en el Grupo BASF trabajan para contribuir al éxito de nuestros clientes en casi todos los sectores y en casi todos los países del mundo. Nuestro portafolio de productos está organizado en seis segmentos: Químicos, Materiales, Soluciones Industriales, Tecnologías de Superficie, Nutrición & Cuidado, y Soluciones Agrícolas. En 2019, BASF generó ventas de €59 mil millones. Las acciones de BASF cotizan en la bolsa de Frankfurt (BAS) y como American Depositary Receipts (BASFY) en los Estados Unidos. Podrá encontrar información adicional en: www.basf.com 

FUENTE BASF

Reporte de Color 2020 de BASF: Una gama más amplia de colores salió de las líneas de ensamble del mundo en 2020

– Ampliando los espacios de color, hacen que el espectro general sea más amplio que en 2019.

– Tonalidades diversas de azul, rojo, amarillo y violeta avanzan en algunas regiones.

– A pesar del cambio en los colores, el blanco, negro, plata y gris siguen un patrón conocido, cubriendo la mayoría de los vehículos producidos.

CIUDAD DE MEXICO, 7 de enero de 2021 /PRNewswire/ — El Reporte de Color 2020 de BASF para Coatings de Automóviles OEM muestra que la paleta de color para automóviles está dando un giro en formas no convencionales,…

– Ampliando los espacios de color, hacen que el espectro general sea más amplio que en 2019.

– Tonalidades diversas de azul, rojo, amarillo y violeta avanzan en algunas regiones.

– A pesar del cambio en los colores, el blanco, negro, plata y gris siguen un patrón conocido, cubriendo la mayoría de los vehículos producidos.

CIUDAD DE MEXICO, 7 de enero de 2021 /PRNewswire/ — El Reporte de Color 2020 de BASF para Coatings de Automóviles OEM muestra que la paleta de color para automóviles está dando un giro en formas no convencionales, revelando una amplia gama de colores cromáticos que llegarán a las líneas de ensamble a nivel mundial.

Color de automóvil “Dark Seltzer” de BASF

Diversas tonalidades como azul y amarillo van avanzando en algunas regiones, mientras que el rojo y violeta van acercándose al primer lugar que tienen los colores acromáticos en otras partes del mundo. Los espacios de color que van creciendo ampliaron el espectro general con respecto a 2019 y agregaron una chispa de brillo.

A pesar del cambio en los colores, los colores acromáticos (blanco, negro, plata y gris) siguieron un patrón conocido, cubriendo la mayoría de los vehículos producidos. Como ha ocurrido durante varios años, el blanco sigue siendo el color de automóviles más popular en todo el mundo. Tiene una belleza clásica, atemporal, y una conexión tanto al ambiente como a la alta tecnología.

La información citada en el reporte muestra una producción total de vehículos menor que la de años pasados. Incluye tiempos en que los fabricantes de automóviles tuvieron que cerrar debido al COVID-19. La pandemia global ha afectado profundamente la economía de la movilidad y el mundo.

EMEA: Mayor diversidad de colores y tonos cromáticos
Europa, Medio Oriente y África (EMEA) sigue la tendencia global de colores cromáticos. En 2020, alrededor del 11% de los vehículos nuevos en EMEA estuvieron pintados de azul, haciéndolo el color cromático más popular. El violeta es un nuevo entrante en el mercado, aumentando aún más la diversidad. Otros colores cromáticos también van ganando popularidad, especialmente en SUVs más pequeñas, al crecer su segmento de mercado.

Parte de la variedad viene de la diversidad de tonos. En EMEA, los fabricantes de vehículos de OEM usaron más de 160 tonos distintos de azul en 2020 en vehículos. El gris ocupa el segundo lugar con 140 tonos. Ambos espacios de color fueron más diversos que el blanco, que solamente tuvo 70 tonos distintos.

En el espectro acromático, el blanco sigue predominando con 28% del mercado, seguido del gris y el negro.

«La variedad de colores cambia con el tamaño. Por ejemplo, si bien el violeta tiene un lugar único en las SUVs de tamaño mediano, no aparece en grandes cantidades en SUVs pequeñas o más grandes,» señaló Mark Gutjahr, director de Diseño de Color Automotriz, EMEA. «Lo opuesto ocurre con el amarillo, que aparece en los muy pequeños y los muy grandes, pero no en los medianos. Estas son posiciones de color específicas y únicas que aparecen y desaparecen en los segmentos.»        

Norteamérica: Más azul, tal como anticipamos
Los compradores de automóviles en Norteamérica tuvieron menos elecciones para los colores cromáticos, pero esto no significa que estén eligiendo menos automóviles, camiones o SUVs cromáticos. El azul ganó más popularidad como color para automóviles en Norteamérica , desplazando al rojo, mientras que el beige y el café salieron de la lista. Esto deja al verde como el único otro color cromático con números significativos en la región.

Los tonos de azul se perciben como más elegantes, y parece que los compradores que en el pasado han elegido el beige se están moviendo hacia los azules o los grises. Los diseñadores de BASF fueron capaces de anticipar esto. Desde 2016, los diseñadores de BASF describieron el azul como «una dirección principal de color para la industria automotriz, la cual ganará participación de mercado en los años siguientes.» Con frecuencia, los diseñadores de automóviles ven los modelos con 3-4 años de anticipación al desarrollar colores, y el mercado ha resultado exactamente como lo predijeron.

«Hay mucho por lo que emocionarse acerca de los colores brillantes que estamos viendo,» señaló Paul Czornij, director de Diseño, Américas. «Tal como predijimos hace tres o cuatro años, el azul está teniendo un momento bajo el sol, y estamos usando algunos efectos y pigmentos muy hermosos que aumentan las posibilidades del tono y la textura en este importante espacio de diseño.»

Asia Pacífico: Surgen el negro y el gris, al tiempo que aparecen colores más brillantes
En Asia Pacífico se ubica el volumen más elevado de producción automotriz del mundo, y constituye un microcosmo en la popularidad del color a nivel global. Si bien cada región es diferente, las preferencias en Asia Pacífico coinciden con los datos a nivel global, y sus colores brillantes reflejan el despertar que están teniendo los colores cromáticos en todos lados.

El blanco sigue siendo el color más popular en la región, cubriendo cerca del 48% de los vehículos producidos. El negro y el gris continúan aumentando, siguiendo una tendencia a tres años para dejar atrás el predominio del blanco.

Si bien los números totales no son enormes, el café, verde y violeta son todos consistentes en popularidad de color. Va a pasar mucho tiempo antes de que compitan con el blanco como el más popular, pero por ahora, se suman a la tremenda diversidad de color en Asia Pacífico.

«La gente en Asia Pacífico realmente disfruta eligiendo el color de sus vehículos. Los colores están muy orientados a la humanidad, flexibles y libres, mostrando la diversidad de la región y su gente,» señaló Chiharu Matsuhara, director de Diseño, Asia Pacífico.

Sudamérica: Los compradores conservadores eligen colores más conservadores
Los colores como el rojo y el azul, que son tan populares en otras regiones del planeta, siguen siendo jugadores en Sudamérica, especialmente entre compradores de automóviles que están intentando expresar su individualidad con autos más deportivos. Lo más significativo es el amor del mercado por los colores acromáticos.

Históricamente, los compradores de automóviles en Sudamérica han elegido colores más tradicionales, menos llamativos. Como en otras regiones, el blanco es, por mucho, el favorito, cubriendo cerca del 39% de los vehículos OEM. La popularidad del gris y del plata es mayor que en otras regiones, con 18% para cada uno. El negro tiene la menor preferencia entre los colores acromáticos, con 12%. En conjunto, los colores acromáticos representan una participación de 87%.

A diferencia de otras regiones, el rojo resalta como el color cromático más presente, con 9%. Diversas tonalidades de azul son importantes a nivel mundial, mientras que, en Sudamérica, el azul representa solamente 2% del mercado. El naranja es un nuevo entrante, el café se sostiene y el beige casi ha desaparecido.

«Las tendencias que son populares en otras partes del mundo se tardan en afianzar en Sudamérica. Aunque es un continente con muchos aspectos de colores en su cultura, la gente tiende a ser más conservadora con sus automóviles,» señaló Marcos Fernandes, director regional de Desarrollo de Negocios, Coatings Automotrices para Sudamérica.

El Reporte de Color 2020 de BASF para Coatings de Automóviles OEM es un análisis de datos de la división de Coatings de BASF con base en la producción automotriz y aplicación de pintura a vehículos ligeros a nivel global en 2020.

Acerca de la división de Coatings de BASF

La división de Coatings de BASF es un experto global en el desarrollo, producción y comercialización de OEM para automóviles y recubrimientos de re-terminado, pinturas decorativas, así como tratamientos innovadores y sustentables para substratos de metal, plástico y vidrio aplicados para superficies en una amplia gama de industrias. El portafolio está completado por el programa «Innovación Más Allá de la Pintura» («Innovation Beyond Paint«) que busca desarrollar nuevos mercados y negocios. Creamos soluciones avanzadas de desempeño e impulsamos el desempeño, diseño y nuevas aplicaciones para cubrir las necesidades de nuestros socios en todo el mundo. BASF comparte habilidades, conocimientos y recursos de equipos interdisciplinarios y globales para beneficio de los clientes, operando una red de colaboración de sitios en Europa, Norteamérica, Sudamérica y Asia Pacífico. En 2019, la división de Coatings obtuvo ventas globales de aproximadamente €3.75 mil millones.

Soluciones más allá de su imaginación – Coatings de BASF. Para obtener más información acerca de la división de Coatings de BASF y sus productos, visite: www.basf-coatings.com.

Acerca de BASF

En BASF, creamos química para un futuro sustentable. Combinamos el éxito económico con la protección del medio ambiente y la responsabilidad social. Más de 117,000 empleados en el Grupo BASF trabajan para contribuir al éxito de nuestros clientes en casi todos los sectores y en casi todos los países del mundo. Nuestro portafolio de productos está organizado en seis segmentos: Químicos, Materiales, Soluciones Industriales, Tecnologías de Superficie, Nutrición & Cuidado, y Soluciones Agrícolas. En 2019, BASF generó ventas de €59 mil millones. Las acciones de BASF cotizan en la bolsa de Frankfurt (BAS) y como American Depositary Receipts (BASFY) en los Estados Unidos. Podrá encontrar información adicional en: www.basf.com 

FUENTE BASF

Reporte de Color 2020 de BASF: Una gama más amplia de colores salió de las líneas de ensamble del mundo en 2020

– Ampliando los espacios de color, hacen que el espectro general sea más amplio que en 2019.

– Tonalidades diversas de azul, rojo, amarillo y violeta avanzan en algunas regiones.

– A pesar del cambio en los colores, el blanco, negro, plata y gris siguen un patrón conocido, cubriendo la mayoría de los vehículos producidos.

CIUDAD DE MEXICO, 7 de enero de 2021 /PRNewswire/ — El Reporte de Color 2020 de BASF para Coatings de Automóviles OEM muestra que la paleta de color para automóviles está dando un giro en formas no convencionales,…

– Ampliando los espacios de color, hacen que el espectro general sea más amplio que en 2019.

– Tonalidades diversas de azul, rojo, amarillo y violeta avanzan en algunas regiones.

– A pesar del cambio en los colores, el blanco, negro, plata y gris siguen un patrón conocido, cubriendo la mayoría de los vehículos producidos.

CIUDAD DE MEXICO, 7 de enero de 2021 /PRNewswire/ — El Reporte de Color 2020 de BASF para Coatings de Automóviles OEM muestra que la paleta de color para automóviles está dando un giro en formas no convencionales, revelando una amplia gama de colores cromáticos que llegarán a las líneas de ensamble a nivel mundial.

Color de automóvil “Dark Seltzer” de BASF

Diversas tonalidades como azul y amarillo van avanzando en algunas regiones, mientras que el rojo y violeta van acercándose al primer lugar que tienen los colores acromáticos en otras partes del mundo. Los espacios de color que van creciendo ampliaron el espectro general con respecto a 2019 y agregaron una chispa de brillo.

A pesar del cambio en los colores, los colores acromáticos (blanco, negro, plata y gris) siguieron un patrón conocido, cubriendo la mayoría de los vehículos producidos. Como ha ocurrido durante varios años, el blanco sigue siendo el color de automóviles más popular en todo el mundo. Tiene una belleza clásica, atemporal, y una conexión tanto al ambiente como a la alta tecnología.

La información citada en el reporte muestra una producción total de vehículos menor que la de años pasados. Incluye tiempos en que los fabricantes de automóviles tuvieron que cerrar debido al COVID-19. La pandemia global ha afectado profundamente la economía de la movilidad y el mundo.

EMEA: Mayor diversidad de colores y tonos cromáticos
Europa, Medio Oriente y África (EMEA) sigue la tendencia global de colores cromáticos. En 2020, alrededor del 11% de los vehículos nuevos en EMEA estuvieron pintados de azul, haciéndolo el color cromático más popular. El violeta es un nuevo entrante en el mercado, aumentando aún más la diversidad. Otros colores cromáticos también van ganando popularidad, especialmente en SUVs más pequeñas, al crecer su segmento de mercado.

Parte de la variedad viene de la diversidad de tonos. En EMEA, los fabricantes de vehículos de OEM usaron más de 160 tonos distintos de azul en 2020 en vehículos. El gris ocupa el segundo lugar con 140 tonos. Ambos espacios de color fueron más diversos que el blanco, que solamente tuvo 70 tonos distintos.

En el espectro acromático, el blanco sigue predominando con 28% del mercado, seguido del gris y el negro.

«La variedad de colores cambia con el tamaño. Por ejemplo, si bien el violeta tiene un lugar único en las SUVs de tamaño mediano, no aparece en grandes cantidades en SUVs pequeñas o más grandes,» señaló Mark Gutjahr, director de Diseño de Color Automotriz, EMEA. «Lo opuesto ocurre con el amarillo, que aparece en los muy pequeños y los muy grandes, pero no en los medianos. Estas son posiciones de color específicas y únicas que aparecen y desaparecen en los segmentos.»        

Norteamérica: Más azul, tal como anticipamos
Los compradores de automóviles en Norteamérica tuvieron menos elecciones para los colores cromáticos, pero esto no significa que estén eligiendo menos automóviles, camiones o SUVs cromáticos. El azul ganó más popularidad como color para automóviles en Norteamérica , desplazando al rojo, mientras que el beige y el café salieron de la lista. Esto deja al verde como el único otro color cromático con números significativos en la región.

Los tonos de azul se perciben como más elegantes, y parece que los compradores que en el pasado han elegido el beige se están moviendo hacia los azules o los grises. Los diseñadores de BASF fueron capaces de anticipar esto. Desde 2016, los diseñadores de BASF describieron el azul como «una dirección principal de color para la industria automotriz, la cual ganará participación de mercado en los años siguientes.» Con frecuencia, los diseñadores de automóviles ven los modelos con 3-4 años de anticipación al desarrollar colores, y el mercado ha resultado exactamente como lo predijeron.

«Hay mucho por lo que emocionarse acerca de los colores brillantes que estamos viendo,» señaló Paul Czornij, director de Diseño, Américas. «Tal como predijimos hace tres o cuatro años, el azul está teniendo un momento bajo el sol, y estamos usando algunos efectos y pigmentos muy hermosos que aumentan las posibilidades del tono y la textura en este importante espacio de diseño.»

Asia Pacífico: Surgen el negro y el gris, al tiempo que aparecen colores más brillantes
En Asia Pacífico se ubica el volumen más elevado de producción automotriz del mundo, y constituye un microcosmo en la popularidad del color a nivel global. Si bien cada región es diferente, las preferencias en Asia Pacífico coinciden con los datos a nivel global, y sus colores brillantes reflejan el despertar que están teniendo los colores cromáticos en todos lados.

El blanco sigue siendo el color más popular en la región, cubriendo cerca del 48% de los vehículos producidos. El negro y el gris continúan aumentando, siguiendo una tendencia a tres años para dejar atrás el predominio del blanco.

Si bien los números totales no son enormes, el café, verde y violeta son todos consistentes en popularidad de color. Va a pasar mucho tiempo antes de que compitan con el blanco como el más popular, pero por ahora, se suman a la tremenda diversidad de color en Asia Pacífico.

«La gente en Asia Pacífico realmente disfruta eligiendo el color de sus vehículos. Los colores están muy orientados a la humanidad, flexibles y libres, mostrando la diversidad de la región y su gente,» señaló Chiharu Matsuhara, director de Diseño, Asia Pacífico.

Sudamérica: Los compradores conservadores eligen colores más conservadores
Los colores como el rojo y el azul, que son tan populares en otras regiones del planeta, siguen siendo jugadores en Sudamérica, especialmente entre compradores de automóviles que están intentando expresar su individualidad con autos más deportivos. Lo más significativo es el amor del mercado por los colores acromáticos.

Históricamente, los compradores de automóviles en Sudamérica han elegido colores más tradicionales, menos llamativos. Como en otras regiones, el blanco es, por mucho, el favorito, cubriendo cerca del 39% de los vehículos OEM. La popularidad del gris y del plata es mayor que en otras regiones, con 18% para cada uno. El negro tiene la menor preferencia entre los colores acromáticos, con 12%. En conjunto, los colores acromáticos representan una participación de 87%.

A diferencia de otras regiones, el rojo resalta como el color cromático más presente, con 9%. Diversas tonalidades de azul son importantes a nivel mundial, mientras que, en Sudamérica, el azul representa solamente 2% del mercado. El naranja es un nuevo entrante, el café se sostiene y el beige casi ha desaparecido.

«Las tendencias que son populares en otras partes del mundo se tardan en afianzar en Sudamérica. Aunque es un continente con muchos aspectos de colores en su cultura, la gente tiende a ser más conservadora con sus automóviles,» señaló Marcos Fernandes, director regional de Desarrollo de Negocios, Coatings Automotrices para Sudamérica.

El Reporte de Color 2020 de BASF para Coatings de Automóviles OEM es un análisis de datos de la división de Coatings de BASF con base en la producción automotriz y aplicación de pintura a vehículos ligeros a nivel global en 2020.

Acerca de la división de Coatings de BASF

La división de Coatings de BASF es un experto global en el desarrollo, producción y comercialización de OEM para automóviles y recubrimientos de re-terminado, pinturas decorativas, así como tratamientos innovadores y sustentables para substratos de metal, plástico y vidrio aplicados para superficies en una amplia gama de industrias. El portafolio está completado por el programa «Innovación Más Allá de la Pintura» («Innovation Beyond Paint«) que busca desarrollar nuevos mercados y negocios. Creamos soluciones avanzadas de desempeño e impulsamos el desempeño, diseño y nuevas aplicaciones para cubrir las necesidades de nuestros socios en todo el mundo. BASF comparte habilidades, conocimientos y recursos de equipos interdisciplinarios y globales para beneficio de los clientes, operando una red de colaboración de sitios en Europa, Norteamérica, Sudamérica y Asia Pacífico. En 2019, la división de Coatings obtuvo ventas globales de aproximadamente €3.75 mil millones.

Soluciones más allá de su imaginación – Coatings de BASF. Para obtener más información acerca de la división de Coatings de BASF y sus productos, visite: www.basf-coatings.com.

Acerca de BASF

En BASF, creamos química para un futuro sustentable. Combinamos el éxito económico con la protección del medio ambiente y la responsabilidad social. Más de 117,000 empleados en el Grupo BASF trabajan para contribuir al éxito de nuestros clientes en casi todos los sectores y en casi todos los países del mundo. Nuestro portafolio de productos está organizado en seis segmentos: Químicos, Materiales, Soluciones Industriales, Tecnologías de Superficie, Nutrición & Cuidado, y Soluciones Agrícolas. En 2019, BASF generó ventas de €59 mil millones. Las acciones de BASF cotizan en la bolsa de Frankfurt (BAS) y como American Depositary Receipts (BASFY) en los Estados Unidos. Podrá encontrar información adicional en: www.basf.com 

FUENTE BASF

Congress Passed A Bill Just Before The Holidays Offering Vital Tax Credit Eligibility For Waste Heat To Power

COSTA MESA, Calif., Jan. 7, 2021 /PRNewswire/ — Clean Energy Technologies, Inc. (OTCQB: CETY), a clean energy company focusing on products and solutions in the energy efficiency and environmental sustainability market, announced today that congress passed a bill just before the holidays that has seemed almost impossible in recent years. Tucked up into the coronavirus stimulus package are provisions that address climate change and promote clean energy spending, and we are excited.

The reason…

COSTA MESA, Calif., Jan. 7, 2021 /PRNewswire/ — Clean Energy Technologies, Inc. (OTCQB: CETY), a clean energy company focusing on products and solutions in the energy efficiency and environmental sustainability market, announced today that congress passed a bill just before the holidays that has seemed almost impossible in recent years. Tucked up into the coronavirus stimulus package are provisions that address climate change and promote clean energy spending, and we are excited.

The reason this bill is so significant is because it represents actual action addressing global warming by Congress in over a decade. This bill allows $35 billion in clean energy spending and requires that the United States phase down emissions of a greenhouse gas. It also requires companies in the United States to decrease production and use of hydrofluorocarbons (HFCs) by 85 percent over the next 15 years.  Not only is this piece of legislation with bipartisan support the most significant relating to clean energy in over a decade, but it also offers vital tax credit eligibility for waste heat to power.

CETY’s Clean Cycle Organic Rankine Cycle (ORC) heat recovery generator is a magnetic bearing waste heat to power technology. According to the Heat is Power Association, waste heat to power (WHP) is the process of recovering heat that is wasted and using it to create power with no combustion or emissions. Due to inefficiencies in factories, homes, cars, and several other places, most of the energy that is accessible is lost. This heat that is lost is often hot air and is considered «waste heat.» Our technology converts heat from a variety of sources into clean, affordable electricity, which can be either sold back to the grid, or offset electrical costs. The Department of Energy (DOE) suggests that in the United States waste heat is the biggest opportunity for industrial energy efficiency and estimates that there are 15 gigawatts of waste heat to power capacity. CETY’s technology and other WHP systems have many benefits, according to the Heat is Power Association, including «improving industrial energy efficiency, improving electrical reliability for key processes, reducing carbon footprints, reducing the cost of purchased electricity and fuel, and generating revenue by selling excess power.»

Included in the bill is crucial tax credit eligibility for WHP systems. For the first time, WHP has become eligible for a 30 percent tax credit. In recent years, investment tax credits helped increase solar and wind development by reducing costs. According to the DOE, recognizing WHP for the Investment Tax Credit would benefit the industry in the United States by increasing efficiency, reducing emissions, and saving money. Simultaneously, we believe it would boost implementation rates of WHP systems, which would lead to the creation of more manufacturing jobs in the United States. Waste heat is important because it is clean energy that is emission free and fuel-free, and therefore should have the same incentives as other renewable sources. 

If the bill passes through the Senate as many have projected, we believe it could bring more attention to WHP systems like ours. With the investment tax credits, costs for WHP projects would be lowered as well. We are optimistic that with the recognition and lowered costs, more companies would benefit and use WHP systems like ours. Thus, we could expect an increase in economic as well as environmental benefits including more American jobs, support vital manufacturing industries in the United States, and reducing our carbon footprint on an overheating planet.

For more information, visit www.heatrecoverysolutions.com and www.corycos.com

About Clean Energy Technologies, Inc. (CETY)

Headquartered in Costa Mesa, California, Clean Energy Technologies (CETY) delivers power from heat and biomass with zero emission and low cost. CETY designs, produces and markets clean energy products & solutions focused on energy efficiency and renewable energy. The Company’s principal product is the Clean Cycle™ magnetic bearing heat recovery generator, offered by CETY’s subsidiary Clean Energy HRS, or Heat Recovery Solutions.

The Clean Cycle™ system captures waste heat from a variety of sources and turns it into electricity that can be used or sold back to the grid. CETY’s proven, reliable technology allows municipal, commercial, and industrial users with heat sources, such as from biomass, industrial processes or energy production, to boost their overall energy efficiency with no additional fuel, no pollutants, and little ongoing maintenance. CETY’s common stock is currently traded on the OTC Market under the symbol CETY.

For more information, visit www.cetyinc.com or www.heatrecoverysolutions.com.

DISCLAIMER

This news release may include forward-looking statements within the meaning of section 27A of the United States Securities Act of 1933, as amended, and Section 21E of the United States Securities and Exchange Act of 1934, as amended, with respect to achieving corporate objectives, developing additional project interests, the company’s analysis of opportunities in the acquisition and development of various project interests and certain other matters. These statements are made under the «Safe Harbor» provisions of the United States Private Securities Litigation Reform Act of 1995 and involve risks and uncertainties which could cause actual results to differ materially from those in the forward-looking statements contained herein.

Contact:
Clean Energy Technologies, Inc.
Kam Mahdi, CEO
949-273-4990 x814
kmahdi@cetyinc.com

Clean Energy Technologies, Inc.
2990 Redhill Avenue
Costa Mesa , CA 92626
949.273.4990 main
949.273.4990 fax
www.cetyinc.com


Cision View original content:http://www.prnewswire.com/news-releases/congress-passed-a-bill-just-before-the-holidays-offering-vital-tax-credit-eligibility-for-waste-heat-to-power-301202850.html

SOURCE Clean Energy Technologies, Inc.

ATRESERIES, the first TV channel to broadcast Velvet Colección in the Americas

MADRID, Jan. 7, 2021 /PRNewswire-HISPANIC PR WIRE/ — Starting January 17 Atreseries will broadcast two seasons of Velvet Colección, the Movistar+ spin-off that will bring the Atresmedia and Bambú Producciones original series to an end. Thus, Atreseries will become the first television channel to bring Velvet Colección to the Americas and will do so after having broadcast the previous four seasons of Velvet consecutively.

<div…

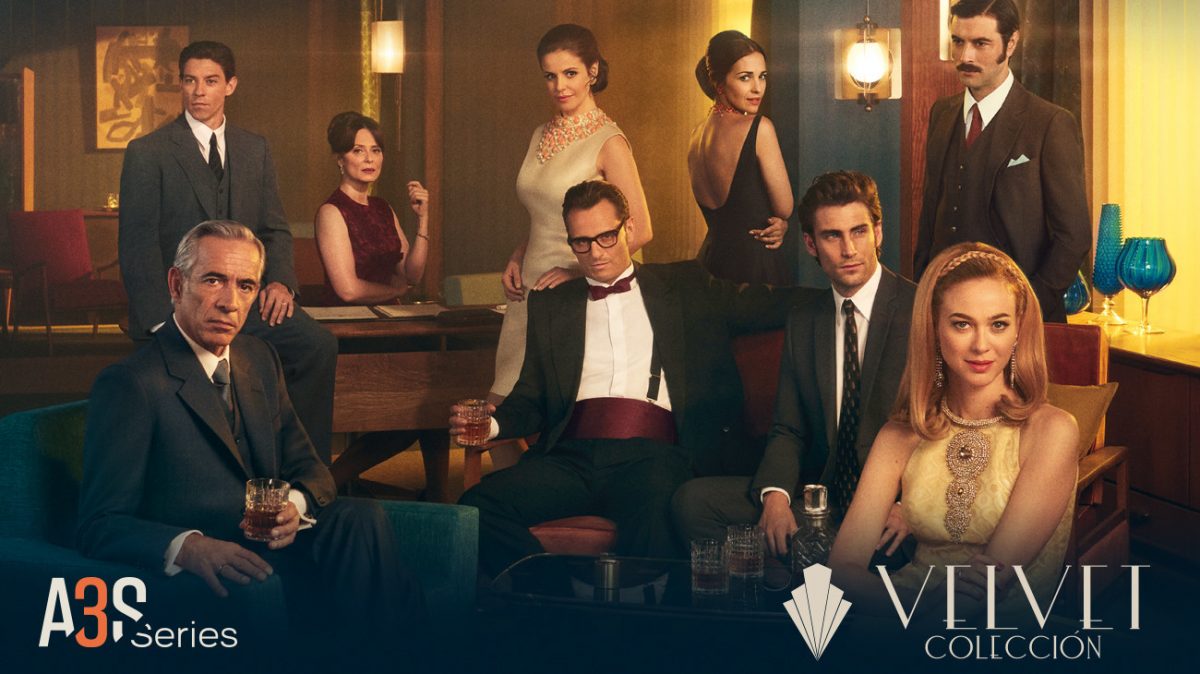
MADRID, Jan. 7, 2021 /PRNewswire-HISPANIC PR WIRE/ — Starting January 17 Atreseries will broadcast two seasons of Velvet Colección, the Movistar+ spin-off that will bring the Atresmedia and Bambú Producciones original series to an end. Thus, Atreseries will become the first television channel to bring Velvet Colección to the Americas and will do so after having broadcast the previous four seasons of Velvet consecutively.

With Velvet Colección, the channel follows the success of one of the most popular fashion boutiques on television and keeps #velvetmania going strong. It will feature a large part of its original cast, led by Marta Hazas, Javier Rey, Aitana Sánchez-Gijón, Adrián Lastra and Asier Etxeandía, as well as participation from Imanol Arias, Mónica Cruz (Un Paso Adelante), Megan Montaner (Sin Identidad), Andrea Duro (Física y Química) y Adriana Ozores (Gran Hotel) y Paula Usero (#Luimelia)

The first of the 20 episodes of Velvet Colección (20×50′) takes place at the end of the 1960s, finding Ana Ribera (Paula Echevarría) settled in New York with her husband (Miguel Ángel Silvestre) and their son. Five years have passed, during which Ana has led the company remotely. But now the time has come for her to return to Spain, follow in the wake of other international companies and take another step forward with her project. It’s clear to Ana that the new challenge is to franchise the prestigious brand, Velvet, and show that she is capable of replicating the model. Barcelona is the city she chooses for the opening of the second Velvet boutique, where all her friends and colleagues will be charged with turning her dreams into reality. But what will undoubtedly be a new success won’t come without problems right from the start. Fate has a tough test in store for the designer.

BROADCAST TIMES
Sundays, starting January 17

Latin America
8 p.m. Mexico/9 p.m. Colombia/10 p.m. Venezuela/11 p.m. Argentina

US
9 p.m. ET /6 p.m. PT

Department of Communications & Public Relations | @Atreseriesint | blanca.aguirre@atresmedia.com | +34 91 623  49 67 | www.atreseries.com

Photo – https://mma.prnewswire.com/media/1395089/VELVET_COLECCION.jpg

SOURCE Atresmedia Internacional

Ardagh Group supplies Rombauer Vineyards with American-made wine bottles

INDIANAPOLIS, Jan. 7, 2021 /PRNewswire/ — Ardagh Group, Glass – North America, a business unit of <a target="_blank"…

INDIANAPOLIS, Jan. 7, 2021 /PRNewswire/ — Ardagh Group, Glass – North America, a business unit of Ardagh Group and the largest domestic manufacturer of glass bottles for the U.S. wine market, announced its first glass production for Rombauer Vineyards from  Ardagh’s Sapulpa, Okla. production facility.

«Purchasing glass bottles that are made in the U.S. gives Rombauer the ability to reinvest in the American economy,» said Andrew Holloway, Associate Winemaker at Rombauer Vineyards. «Having worked with Ardagh multiple years, we were confident in their transition to a new production facility and maintaining the same high-quality glass we have become accustomed to year in and year out. Their dedication to exceptional glass production makes it a great partnership that allows us to have peace of mind that our glass will arrive on time and to the standard we expect.»

In order to service the growing wine market, Ardagh expanded its production for wine bottles to its Sapulpa, Okla., facility, including the bottles manufactured for Rombauer Vineyards.

«Ardagh’s premium wine bottles for Rombauer Vineyards signify the brand’s reputation for quality and sustainability, and Ardagh takes great pride in this partnership,» said John T Shaddox, Chief Commercial Officer for Ardagh’s North American Glass business unit. «Our expanded production capabilities allow us to provide customers with a shorter, less complex supply chain and a stable supply of high-quality glass bottles.»

For more than 125 years, Ardagh has been producing 100 percent and endlessly recyclable glass bottles in the U.S. and offers a wide selection of premium wine bottles in a variety of colors, sizes, styles and finishes.

«We use a very challenging color of glass for our chardonnay – dead leaf green,» said Holloway. «Ardagh was able to provide consistency in the color and shape of the glass so we could run as efficiently as possible. Not only does Ardagh glass look great for our brand, but it also allows us to maximize efficiency when bottling.»

Ardagh will showcase its capabilities to the wine market at the virtual Unified Wine & Grape Symposium from Jan. 26-29, 2021.

To view Ardagh’s extensive wine bottle stock portfolio, which are all made in the U.S.A., visit ardaghgroup.com/wine2020.

Customers interested in purchasing wine bottles can contact Ardagh at 707-200-9350 (West) or 317-558-1585 (Central/East) or marketing.glass.na@ardaghgroup.com.             

Download image here.

Rombauer Vineyards is a Napa Valley based, family-owned winery founded in 1980 by Koerner and Joan Rombauer. Dedicated to providing gracious hospitality, the Rombauer family and staff take pride in creating joyful moments for their customers across the country and at their Napa Valley and Sierra Foothills tasting rooms. Rombauer owns and sustainably farms over 670 acres of vineyards in Carneros, Atlas Peak, Stags Leap, St. Helena, Calistoga and the Sierra Foothills. Rombauer’s Chardonnays, Merlot, Cabernet Sauvignons, Zinfandels and Sauvignon Blanc are beloved by wine enthusiasts around the world. www.rombauer.com 

Further information:
Gina Behrman, Vice President, Marketing, Communications & NPD at Ardagh Group, Glass – North America, gina.l.behrman@ardaghgroup.com,  317.558.5717

Paula Polei, Manager, Marketing & Communications at Ardagh Group, Glass – North America, paula.polei@ardaghgroup.com,  317.558.5732

Andrew Holloway, Associate Winemaker at Rombauer Vineyards,   Andrewh@rombauer.com, 707.963.6651


Cision View original content to download multimedia:http://www.prnewswire.com/news-releases/ardagh-group-supplies-rombauer-vineyards-with-american-made-wine-bottles-301197164.html

SOURCE Ardagh Group

Services PMI™ at 57.2%; December 2020 Services ISM® Report On Business®

Business Activity Index at 59.4%; New Orders Index at 58.5%; Employment Index at 48.2%; Supplier Deliveries Index at 62.8%

TEMPE, Ariz., Jan. 7, 2021 /PRNewswire/ — Economic activity in the services sector grew in December for the seventh month in a row, say the nation’s purchasing and supply executives in the latest Services ISM® Report On Business®.

The report was issued today by Anthony Nieves, CPSM,…

Business Activity Index at 59.4%; New Orders Index at 58.5%; Employment Index at 48.2%; Supplier Deliveries Index at 62.8%

TEMPE, Ariz., Jan. 7, 2021 /PRNewswire/ — Economic activity in the services sector grew in December for the seventh month in a row, say the nation’s purchasing and supply executives in the latest Services ISM® Report On Business®.

The report was issued today by Anthony Nieves, CPSM, C.P.M., A.P.P., CFPM, Chair of the Institute for Supply Management® (ISM®) Services Business Survey Committee: «The Services PMI registered 57.2 percent, 1.3 percentage points higher than the November reading of 55.9 percent. This reading represents a seventh straight month of growth for the services sector, which has expanded for all but two of the last 131 months.

«The Supplier Deliveries Index registered 62.8 percent, up 5.8 percentage points from November’s reading of 57 percent. (Supplier Deliveries is the only ISM®Report On Business® index that is inversed; a reading of above 50 percent indicates slower deliveries, which is typical as the economy improves and customer demand increases.)

«The Prices Index figure of 64.8 percent is 1.3 percentage points lower than the November reading of 66.1 percent, indicating that prices increased in December, and at a slower rate. According to the Services PMI, 14 services industries reported growth. The composite index indicated growth for the seventh consecutive month after a two-month contraction in April and May. In December, a slight uptick in the rate of services-sector growth continued. Respondents’ comments are mixed about business conditions and the economy. Various local- and state-level COVID-19 shutdowns continue to negatively impact companies and industries. Applicable human resources, production capacity and logistics have been more constrained than during the previous month. Most respondents are cautiously optimistic about business conditions with the recent approval and impending distribution of vaccines,» says Nieves.

INDUSTRY PERFORMANCE
The 14 services industries reporting growth in December — listed in order — are: Management of Companies & Support Services; Wholesale Trade; Retail Trade; Health Care & Social Assistance; Transportation & Warehousing; Finance & Insurance; Utilities; Agriculture, Forestry, Fishing & Hunting; Information; Professional, Scientific & Technical Services; Mining; Public Administration; Construction; and Educational Services. The four industries reporting contraction in December are: Arts, Entertainment & Recreation; Accommodation & Food Services; Other Services; and Real Estate, Rental & Leasing.

WHAT RESPONDENTS ARE SAYING

  • «Starting to see demand weakening as states go back to shut down. Will look to see business resume in late first quarter, as vaccine distribution takes place.» (Accommodation & Food Services)
  • «Lack of labor continues to be a significant drag on the business. We have plenty of work but are now considering rejecting some orders due to shrinking capacity.» (Construction)
  • «Continued local and state shutdowns negatively impacting a variety of operations. Notably, shipping delays are beginning to affect operations as [parcel companies] all struggle under the strain of holiday-shipping demand. Construction and services continue to also be challenged, as COVID-19 infections become more pervasive with workers calling out to quarantine, etc.» (Educational Services)
  • «COVID-19 continues to be an impediment to normalized business operations, and the pandemic is not abating — only worsening as [we] get into the winter months. Stocks of personal protective equipment [PPE] are adequate but not sufficient for most categories, with the exception of nitrile exam gloves, which are in extremely short supply internationally. Our hospital system achieved 94- percent capacity in our intensive care units and continued to hover around that number with new admissions, fatalities and discharges on a daily basis. This situation continues to impede normal revenue-generating surgical volumes.» (Health Care & Social Assistance)
  • «Deliveries as a whole, are slowing down considerably. Between COVID-19, the holidays, and inclement weather of late, the remainder of [2020] stands to be very challenging regarding maintaining adequate materials for operations.» (Professional, Scientific & Technical Services)
  • «Business quite good, all things considered, although below the original 2020 planned forecast.» (Real Estate, Rental & Leasing)
  • «Business conditions are improving with increased volume, but [growth has] slowed slightly due to COVID-19 shutdowns in some states.» (Transportation & Warehousing)
  • «The general business conditions are steady/stable. Expecting a very slight slowdown to end the year, with a rebound in mid-January.» (Utilities)
  • «We have seen a growing number of product shortages and increased lead times during the last quarter.» (Wholesale Trade)


ISM® SERVICES SURVEY RESULTS AT A GLANCE

COMPARISON OF ISM® SERVICES AND ISM® MANUFACTURING SURVEYS

December 2020

Index

 Services PMI

Manufacturing PMI®

Series
Index

Dec

Series
Index

Nov

Percent
Point
Change

Direction

Rate of
Change

Trend**

(Months)

Series
Index

Dec

Series
Index

Nov

Percent
Point
Change

Services PMI

57.2

55.9

+1.3

Growing

Faster

7

60.7

57.5

+3.2

Business Activity/

Production

59.4

58.0

+1.4

Growing

Faster

7

64.8

60.8

+4.0

New Orders

58.5

57.2

+1.3

Growing

Faster

7

67.9

65.1

+2.8

Employment

48.2

51.5

-3.3

Contracting

From Growing

1

51.5

48.4

+3.1

Supplier Deliveries

62.8

57.0

+5.8

Slowing

Faster

19

67.6

61.7

+5.9

Inventories

58.2

49.3

+8.9

Growing

From Contracting

1

51.6

51.2

+0.4

Prices

64.8

66.1

-1.3

Increasing

Slower

9

77.6

65.4

+12.2

Backlog of Orders

48.7

50.7

-2.0

Contracting

From Growing

1

59.1

56.9

+2.2

New Export Orders

57.3

50.4

+6.9

Growing

Faster

5

57.5

57.8

-0.3

Imports

51.8

55.0

-3.2

Growing

Slower

3

54.6

55.1

-0.5

Inventory Sentiment

47.7

49.9

-2.2

Too Low

Faster

2

N/A

N/A

N/A

Customers’ Inventories

N/A

N/A

N/A

N/A

N/A

N/A

37.9

36.3

+1.6

Overall Economy

Growing

Faster

7

Services Sector

Growing

Faster

7

Services ISM® Report On Business® data is seasonally adjusted for the Business Activity, New Orders, Prices and Employment indexes. Manufacturing ISM® Report On Business® data is seasonally adjusted for New Orders, Production, Employment and Inventories indexes.
**Number of months moving in current direction.

COMMODITIES REPORTED UP/DOWN IN PRICE, AND IN SHORT SUPPLY

Commodities Up in Price
Copper Products; Copper Wire; Construction Contractors (3); Diesel; Disinfectant Supplies (4); Exam Gloves (3); Freight; Gasoline; Gloves; Labor; Labor — Construction; Medical Supplies (11); Nitrile Gloves (4); Oriented Strand Board; Personal Protective Equipment (PPE) (11); PPE — Gloves (3); PPE — Gowns (3); Plastic Products (3); PVC Products (4); Shingles; and Steel (4).

Commodities Down in Price
None.

Commodities in Short Supply
Construction Contractors (3); Disinfectant Supplies (2); Electrical Components; Exam Gloves (3); Gloves; Labor; N95 Masks (10); Needles & Syringes; Nitrile Gloves (7); Personal Protective Equipment (PPE) (11); PPE — Gloves (9); PPE — Gowns (9); Plastic Products; PVC Products (3); Steel; Steel Products; and Sterile Water.

Note: The number of consecutive months the commodity is listed is indicated after each item.

DECEMBER 2020 SERVICES INDEX SUMMARIES

Services PMI

In December, the Services PMI registered 57.2 percent, 1.3 percentage points higher than November’s figure of 55.9 percent. This reading indicates the services sector grew for the seventh consecutive month after two months of contraction and 122 months of growth before that. A reading above 50 percent indicates the services sector economy is generally expanding; below 50 percent indicates the services sector is generally contracting.

A Services PMI above 48.5 percent, over time, generally indicates an expansion of the overall economy. Therefore, the December Services PMI™ indicates expansion for a seventh straight month following two months of contraction and a preceding period of 128 months of growth. Nieves says, «The past relationship between the Services PMI and the overall economy indicates that the Services PMI for December (57.2 percent) corresponds to a 2.9-percent increase in real gross domestic product (GDP) on an annualized basis.»

SERVICES PMI™ HISTORY

Month

Services PMI

Month

Services PMI

Dec 2020

57.2

Jun 2020

57.1

Nov 2020

55.9

May 2020

45.4

Oct 2020

56.6

Apr 2020

41.8

Sep 2020

57.8

Mar 2020

52.5

Aug 2020

56.9

Feb 2020

57.3

Jul 2020

58.1

Jan 2020

55.5

Average for 12 months – 54.3

High – 58.1

Low – 41.8

Business Activity
ISM®‘s Business Activity Index registered 59.4 percent in December, an increase of 1.4 percentage points from the November reading of 58 percent. This represents growth for the seventh consecutive month. Comments from respondents include: «Indications are showing potential improvement, but many people are working from home, restricting demand» and «Seasonal sales have increased business activity as expected.»

The 11 industries reporting an increase in business activity for the month of December — listed in order — are: Management of Companies & Support Services; Health Care & Social Assistance; Transportation & Warehousing; Information; Retail Trade; Agriculture, Forestry, Fishing & Hunting; Mining; Wholesale Trade; Finance & Insurance; Professional, Scientific & Technical Services; and Utilities. The five industries reporting a decrease are: Other Services; Accommodation & Food Services; Real Estate, Rental & Leasing; Construction; and Educational Services.

Business Activity

%Higher

%Same

%Lower

Index

Dec 2020

31.4

50.4

18.2

59.4

Nov 2020

27.5

57.0

15.4

58.0

Oct 2020

39.4

45.5

15.1

61.2

Sep 2020

36.5

55.6

7.8

63.0

New Orders
ISM®‘s New Orders Index registered 58.5 percent, an increase of 1.3 percentage points from the November reading of 57.2 percent. New orders grew for the seventh consecutive month after two months of contraction and a preceding period of 128 months of expansion. Comments from respondents include: «We are in peak season, and revenue seems pretty consistent» and «End-of-year spending.»

The 10 industries reporting growth of new orders in December — listed in order — are: Management of Companies & Support Services; Retail Trade; Health Care & Social Assistance; Transportation & Warehousing; Wholesale Trade; Finance & Insurance; Information; Construction; Public Administration; and Professional, Scientific & Technical Services. The five industries reporting a decrease in December are: Arts, Entertainment & Recreation; Real Estate, Rental & Leasing; Agriculture, Forestry, Fishing & Hunting; Accommodation & Food Services; and Other Services.

New Orders

%Higher

%Same

%Lower

Index

Dec 2020

30.3

49.9

19.7

58.5

Nov 2020

29.6

55.2

15.1

57.2

Oct 2020

32.3

49.8

18.0

58.8

Sep 2020

37.2

50.9

12.0

61.5

Employment
Employment activity in the services sector contracted in December after three consecutive months of growth. (After 72 straight pre-pandemic months of expansion, the index contracted from March through August.) ISM®‘s Services Employment Index registered 48.2 percent in December, down 3.3 percentage points from the November reading of 51.5 percent. Comments from respondents include: «Less staff needed in restaurants due to restrictions» and «We had to reduce our workforce even further.»

The four industries reporting an increase in employment in December are: Management of Companies & Support Services; Wholesale Trade; Utilities; and Finance & Insurance. The 10 industries that reported a reduction in employment in December — listed in order — are: Arts, Entertainment & Recreation; Real Estate, Rental & Leasing; Mining; Accommodation & Food Services; Professional, Scientific & Technical Services; Transportation & Warehousing; Other Services; Information; Construction; and Health Care & Social Assistance.

Employment

%Higher

%Same

%Lower

Index

Dec 2020

14.6

66.8

18.6

48.2

Nov 2020

16.0

69.6

14.5

51.5

Oct 2020

19.5

62.4

18.1

50.1

Sep 2020

17.1

68.0

14.9

51.8

Supplier Deliveries
The Supplier Deliveries Index registered 62.8 percent, which is 5.8 percentage points higher than the 57 percent reported in November. A reading above 50 percent indicates slower deliveries, while a reading below 50 percent indicates faster deliveries. Comments from respondents include: «Suppliers impacted by supply chain disruptions for core components and increased ordering of certain tools and equipment,» «General freight delays given volume constraint issues with parcel delivery,» and «End-of-year push in conjunction with holidays is causing an increased strain on [the] shipping industry.»

The 17 industries reporting slower deliveries in December — listed in order — are: Wholesale Trade; Real Estate, Rental & Leasing; Agriculture, Forestry, Fishing & Hunting; Management of Companies & Support Services; Retail Trade; Professional, Scientific & Technical Services; Health Care & Social Assistance; Utilities; Accommodation & Food Services; Mining; Construction; Other Services; Transportation & Warehousing; Educational Services; Public Administration; Finance & Insurance; and Information. No industry reported faster deliveries in December.

Supplier
Deliveries

%Slower

%Same

%Faster

Index

Dec 2020

27.6

70.4

2.0

62.8

Nov 2020

16.9

80.3

2.8

57.0

Oct 2020

15.4

81.4

3.1

56.2

Sep 2020

18.1

73.7

8.2

54.9

Inventories
The Inventories Index grew substantially in December after a month of contraction. The reading of 58.2 percent was an 8.9-percentage point increase from the 49.3 percent reported in November. Of the total respondents in December, 46 percent indicated they do not have inventories or do not measure them. Comments from respondents include: «Building inventory when and where possible to mitigate supply chain risks like supplier plant disruptions, carrier-related delays and the holidays; however, inventories remain fairly steady» and «Inventories were previously too low.»

The 11 industries reporting an increase in inventories in December — listed in order — are: Arts, Entertainment & Recreation; Agriculture, Forestry, Fishing & Hunting; Accommodation & Food Services; Retail Trade; Real Estate, Rental & Leasing; Utilities; Health Care & Social Assistance; Wholesale Trade; Public Administration; Professional, Scientific & Technical Services; and Educational Services. The five industries reporting a decrease in inventories in December are: Other Services; Mining; Construction; Transportation & Warehousing; and Information.

Inventories

%Higher

%Same

%Lower

Index

Dec 2020

28.6

59.2

12.2

58.2

Nov 2020

19.6

59.4

21.0

49.3

Oct 2020

22.5

61.2

16.3

53.1

Sep 2020

20.6

56.5

22.9

48.8

Prices
Prices paid by service organizations for materials and services increased in December, with the index registering 64.8 percent. This is 1.3 percentage points lower than the 66.1 percent reported in November.

The 12 Services industries that reported an increase in prices paid during the month of December — listed in order — are: Accommodation & Food Services; Transportation & Warehousing; Wholesale Trade; Agriculture, Forestry, Fishing & Hunting; Health Care & Social Assistance; Finance & Insurance; Management of Companies & Support Services; Real Estate, Rental & Leasing; Mining; Public Administration; Utilities; and Professional, Scientific & Technical Services. The two industries that reported a decrease in prices paid for December are: Other Services; and Information.

Prices

%Higher

%Same

%Lower

Index

Dec 2020

26.5

68.4

5.1

64.8

Nov 2020

32.0

62.2

5.8

66.1

Oct 2020

30.7

63.4

5.9

63.9

Sep 2020

24.1

69.8

6.0

59.0

NOTE: Commodities reported as up in price and down in price are listed in the commodities section of this report.

Backlog of Orders
The ISM® Services Backlog of Orders Index contracted in December after six months of growth. The index registered 48.7 percent, 2 percentage points lower than the 50.7 percent reported in November. Of the total respondents in December, 44 percent indicated they do not measure backlog of orders.

The seven industries reporting an increase in order backlogs in December — listed in order — are: Construction; Transportation & Warehousing; Retail Trade; Health Care & Social Assistance; Wholesale Trade; Finance & Insurance; and Professional, Scientific & Technical Services. The seven industries that reported a decrease in backlogs in December — listed in order — are: Arts, Entertainment & Recreation; Agriculture, Forestry, Fishing & Hunting; Real Estate, Rental & Leasing; Other Services; Public Administration; Educational Services; and Utilities.

Backlog of
Orders

%Higher

%Same

%Lower

Index

Dec 2020

15.2

67.0

17.8

48.7

Nov 2020

19.0

63.3

17.6

50.7

Oct 2020

21.3

66.2

12.5

54.4

Sep 2020

14.6

70.9

14.5

50.1

New Export Orders
Orders and requests for services and other non-manufacturing activities to be provided outside of the U.S. by domestically based companies grew in December for the fifth consecutive month. The New Export Orders Index registered 57.3 percent in December, which is 6.9 percentage points higher than the 50.4 percent reported in November. Of the total respondents in December, 74 percent indicated they either do not perform, or do not separately measure, orders for work outside of the U.S.

The seven industries reporting an increase in new export orders in December — listed in order — are: Transportation & Warehousing; Educational Services; Real Estate, Rental & Leasing; Finance & Insurance; Wholesale Trade; Professional, Scientific & Technical Services; and Information. The three industries that reported a decrease in exports in December are: Other Services; Utilities; and Health Care & Social Assistance. Eight industries reported no change in December.

New Export
Orders

%Higher

%Same

%Lower

Index

Dec 2020

20.2

74.2

5.6

57.3

Nov 2020

15.0

70.8

14.2

50.4

Oct 2020

19.9

67.6

12.5

53.7

Sep 2020

18.1

69.0

12.9

52.6

Imports
The Imports Index grew at a slower rate in December, as it registered 51.8 percent, 3.2 percentage points lower than November’s figure of 55 percent. Seventy-two percent of respondents reported that they do not use, or do not track the use of, imported materials.

The four industries reporting an increase in imports for the month of December are: Transportation & Warehousing; Wholesale Trade; Information; and Utilities. The two industries reporting a decrease in imports in December are: Mining; and Accommodation & Food Services. Twelve industries reported no change.

Imports

%Higher

%Same

%Lower

Index

Dec 2020

8.8

86.0

5.2

51.8

Nov 2020

17.3

75.3

7.4

55.0

Oct 2020

10.1

84.8

5.1

52.5

Sep 2020

8.7

75.8

15.4

46.6

Inventory Sentiment
The ISM® Services Inventory Sentiment Index in December registered 47.7 percent, which is 2.2 percentage points lower than the 49.9 percent reading in November. This is only the third month — the others are March and November 2020 — in which respondents indicated they believe their inventories are too low since the inception of the Services (formerly Non-Manufacturing) Report On Business® in 1997.

The six industries reporting sentiment that their inventories were too high in December — listed in order — are: Arts, Entertainment & Recreation; Mining; Other Services; Utilities; Educational Services; and Health Care & Social Assistance. The four industries reporting a feeling that their inventories were too low in December are: Real Estate, Rental & Leasing; Public Administration; Transportation & Warehousing; and Professional, Scientific & Technical Services. Eight industries reported no change in inventory sentiment in December.

Inventory
Sentiment

%Too

High

%About
Right

%Too

Low

Index

Dec 2020

10.2

75.1

14.8

47.7

Nov 2020

12.3

75.3

12.4

49.9

Oct 2020

14.0

74.2

11.8

51.1

Sep 2020

18.3

74.3

7.4

55.4

About This Report
DO NOT CONFUSE THIS NATIONAL REPORT with the various regional purchasing reports released across the country. The national report’s information reflects the entire U.S., while the regional reports contain primarily regional data from their local vicinities. Also, the information in the regional reports is not used in calculating the results of the national report. The information compiled in this report is for the month of December 2020.

The data presented herein is obtained from a survey of supply executives in the services sector based on information they have collected within their respective organizations. ISM® makes no representation, other than that stated within this release, regarding the individual company data collection procedures. The data should be compared to all other economic data sources when used in decision-making.

Data and Method of Presentation
The Services ISM® Report On Business® (formerly the Non-Manufacturing ISM® Report On Business®) is based on data compiled from purchasing and supply executives nationwide. Membership of the Services Business Survey Committee (formerly Non-Manufacturing Business Survey Committee) is diversified by NAICS, based on each industry’s contribution to gross domestic product (GDP). The Services Business Survey Committee responses are divided into the following NAICS code categories: Agriculture, Forestry, Fishing & Hunting; Mining; Utilities; Construction; Wholesale Trade; Retail Trade; Transportation & Warehousing; Information; Finance & Insurance; Real Estate, Rental & Leasing; Professional, Scientific & Technical Services; Management of Companies & Support Services; Educational Services; Health Care & Social Assistance; Arts, Entertainment & Recreation; Accommodation & Food Services; Public Administration; and Other Services (services such as Equipment & Machinery Repairing; Promoting or Administering Religious Activities; Grantmaking; Advocacy; and Providing Dry-Cleaning & Laundry Services, Personal Care Services, Death Care Services, Pet Care Services, Photofinishing Services, Temporary Parking Services, and Dating Services).

Survey responses reflect the change, if any, in the current month compared to the previous month. For each of the indicators measured (Business Activity, New Orders, Backlog of Orders, New Export Orders, Inventory Change, Inventory Sentiment, Imports, Prices, Employment and Supplier Deliveries), this report shows the percentage reporting each response and the diffusion index. Responses represent raw data and are never changed. Data is seasonally adjusted for Business Activity, New Orders, Prices and Employment. All seasonal adjustment factors are subject annually to relatively minor changes when conditions warrant them. The remaining indexes have not indicated significant seasonality.

The Services PMI is a composite index based on the diffusion indexes for four of the indicators with equal weights: Business Activity (seasonally adjusted), New Orders (seasonally adjusted), Employment (seasonally adjusted) and Supplier Deliveries. Diffusion indexes have the properties of leading indicators and are convenient summary measures showing the prevailing direction of change and the scope of change. An index reading above 50 percent indicates that the services economy is generally expanding; below 50 percent indicates that it is generally declining. Supplier Deliveries is an exception. A Supplier Deliveries Index above 50 percent indicates slower deliveries and below 50 percent indicates faster deliveries.

A Services PMI above 48.5 percent, over time, indicates that the overall economy, or gross domestic product (GDP), is generally expanding; below 48.5 percent, it is generally declining. The distance from 50 percent or 48.5 percent is indicative of the strength of the expansion or decline.

The Services ISM® Report On Business® survey is sent out to Services Business Survey Committee respondents the first part of each month. Respondents are asked to ONLY report on U.S. operations for the current month. ISM® receives survey responses throughout most of any given month, with the majority of respondents generally waiting until late in the month to submit responses to give the most accurate picture of current business activity. ISM® then compiles the report for release on the third business day of the following month.

The industries reporting growth, as indicated in the Services ISM® Report On Business® monthly report, are listed in the order of most growth to least growth. For the industries reporting contraction or decreases, those are listed in the order of the highest level of contraction/decrease to the least level of contraction/decrease.

ISM ROB Content
The Institute for Supply Management® («ISM») Report On Business® (Manufacturing, Services and Hospital reports) («ISM ROB») contains information, text, files, images, video, sounds, musical works, works of authorship, applications, and any other materials or content (collectively, «Content») of ISM («ISM ROB Content»). ISM ROB Content is protected by copyright, trademark, trade secret, and other laws, and as between you and ISM, ISM owns and retains all rights in the ISM ROB Content. ISM hereby grants you a limited, revocable, nonsublicensable license to access and display on your individual device the ISM ROB Content (excluding any software code) solely for your personal, non-commercial use. The ISM ROB Content shall also contain Content of users and other ISM licensors. Except as provided herein or as explicitly allowed in writing by ISM, you shall not copy, download, stream, capture, reproduce, duplicate, archive, upload, modify, translate, publish, broadcast, transmit, retransmit, distribute, perform, display, sell, or otherwise use any ISM ROB Content.

Except as explicitly and expressly permitted by ISM, you are strictly prohibited from creating works or materials (including, but not limited to: tables, charts, data streams, time-series variables, fonts, icons, link buttons, wallpaper, desktop themes, online postcards, montages, mashups and similar videos, greeting cards, and unlicensed merchandise) that derive from or are based on the ISM ROB Content. This prohibition applies regardless of whether the derivative works or materials are sold, bartered, or given away. You shall not either directly or through the use of any device, software, internet site, web-based service, or other means remove, alter, bypass, avoid, interfere with, or circumvent any copyright, trademark, or other proprietary notices marked on the Content or any digital rights management mechanism, device, or other content protection or access control measure associated with the Content including geo-filtering mechanisms. Without prior written authorization from ISM, you shall not build a business utilizing the Content, whether or not for profit.

You shall not create, recreate, distribute, incorporate in other work, or advertise an index of any portion of the Content unless you receive prior written authorization from ISM. Requests for permission to reproduce or distribute ISM ROB Content can be made by contacting in writing at: ISM Research, Institute for Supply Management, 309 W. Elliot Road, Suite 113, Tempe, AZ 85284-1556, or by emailing kcahill@ismworld.org; subject: Content Request.

ISM shall not have any liability, duty, or obligation for or relating to the ISM ROB Content or other information contained herein, any errors, inaccuracies, omissions or delays in providing any ISM ROB Content, or for any actions taken in reliance thereon. In no event shall ISM be liable for any special, incidental, or consequential damages, arising out of the use of the ISM ROB. Report On Business®, Manufacturing PMI®, Services PMI, and Hospital PMI are registered trademarks of Institute for Supply Management®. Institute for Supply Management® and ISM® are registered trademarks of Institute for Supply Management, Inc.

About Institute for Supply Management®
Institute for Supply Management® (ISM®) serves supply management professionals in more than 90 countries. Its 50,000 members around the world manage about US$1 trillion in corporate and government supply chain procurement annually. Founded in 1915 as the first supply management institute in the world, ISM is committed to advancing the practice of supply management to drive value and competitive advantage for its members, contributing to a prosperous and sustainable world. ISM leads the profession through the ISM Report On Business®, its highly regarded certification programs and the ISM Mastery Model®. This report has been issued by the association since 1931, except for a four-year interruption during World War II.

The full text version of the Services ISM® Report On Business® is posted on ISM®‘s website at www.ismrob.org on the third business day* of every month after 10:00 a.m. ET.

The next Services ISM® Report On Business® featuring January 2021 data will be released at 10:00 a.m. ET on Wednesday, February 3, 2021.

*Unless the New York Stock Exchange is closed.

Contact:

Kristina Cahill

Report On Business® Analyst

ISM®, ROB/Research Manager

Tempe, Arizona

+1 480.455.5910

Email: kcahill@ismworld.org


Institute for Supply Management logo. (PRNewsFoto/Institute for Supply Management)


Cision View original content to download multimedia:http://www.prnewswire.com/news-releases/services-pmi-at-57-2-december-2020-services-ism-report-on-business-301202370.html

SOURCE Institute for Supply Management

Freedom Forever Shows Significant Growth Despite Global Pandemic

TEMECULA, Calif., Jan. 7, 2021 /PRNewswire/ — 2020 has been a year that none of us will ever forget. Despite hardships caused by the year’s challenges, including a global pandemic, political and legislative turmoil, Freedom Forever had an incredible year of growth. As previously reported, Freedom Forever…

TEMECULA, Calif., Jan. 7, 2021 /PRNewswire/ — 2020 has been a year that none of us will ever forget. Despite hardships caused by the year’s challenges, including a global pandemic, political and legislative turmoil, Freedom Forever had an incredible year of growth. As previously reported, Freedom Forever was named one of Silicon Review’s 50 most admired companies, earned a spot on Solar Power World’s Top Solar Contractor’s list, and secured a place on INC Magazine’s list of the 500 fastest-growing companies in the US, for the 3rd time in a row. All of this is thanks to a solid customer base, tenacious employees, and a strong family of independent authorized dealers.

Freedom Forever started 2020 operating in 8 states. By the end of the year, they had grown their business into a total of 20 states. Many companies are struggling during the pandemic, and Freedom Forever has had its share of challenges as well. But those challenges were met head-on, and the company was able to increase its workforce by over 65%. «We are grateful that our success enabled us to provide good-paying jobs all across America during a time when the need for opportunity has never been greater. We expanded our offices in states across the country; we started with 11 branches, and now, we have 25,» said Brett Bouchy, CEO.

«Freedom Forever helped 12,875 families go solar and save money on electricity this year. Thanks to our customers, we installed 347,442 panels that can produce 102 megawatts of electricity! That number of panels and amount of power is double what we did in 2019. We are truly blessed to see this amount of growth in a time like this,» said Brian Eglsaer, who was recently named Freedom Forever’s Chief Operations Officer. He added, «this year alone, Freedom Forever customers helped keep 156,000 metric tons of Carbon Dioxide out of the atmosphere. That’s equivalent to 34,000 passenger vehicles driven for a year. It’s awe-inspiring.»

«We’ve accomplished a lot, and we are just getting started,» Bouchy proclaimed. Looking forward to 2021 and beyond, Freedom Forever aims to open in most US states. «We are excited about the possibilities offered by solar energy storage systems to provide our customers more freedom than ever from high utility bills, and we look forward to being an important part of America’s switch to renewable energy.»

About Freedom Forever:
Freedom Forever is focused on residential solar installations that deliver best-in-class Engineering, Procurement, and Construction for its dealer network. Since 2011, Freedom Forever has enabled its dealer network to succeed with a premium offering and aggressive pricing flexibility. Freedom Forever’s 25-year production guarantee provides the ultimate peace-of-mind for homeowners reluctant to make a big investment. With Freedom Forever, homeowners know what they’re getting every time. For more information, please visit freedomforever.com.

Cision View original content to download multimedia:http://www.prnewswire.com/news-releases/freedom-forever-shows-significant-growth-despite-global-pandemic-301202514.html

SOURCE Freedom Forever

Augwind to build 120 MWh electricity storage systems in one of the world’s largest Energy Storage tenders

YAKUM, Israel, Jan. 7, 2021 /PRNewswire/ — Augwind (TASE: AUGN) is a company specializing in developing and integrating storage technologies for the electricity market, including from renewable sources such as PV or wind power that incorporate AirBattery, the energy storage system designed by Augwind.

Augwind announced today the winning of a sizeable governmental tender that was led in Israel by the Government’s Electricity Authority, in a scale of 2.5 GWh…

YAKUM, Israel, Jan. 7, 2021 /PRNewswire/ — Augwind (TASE: AUGN) is a company specializing in developing and integrating storage technologies for the electricity market, including from renewable sources such as PV or wind power that incorporate AirBattery, the energy storage system designed by Augwind.

Augwind announced today the winning of a sizeable governmental tender that was led in Israel by the Government’s Electricity Authority, in a scale of 2.5 GWh storage.

Augwind has expanded the relations with Solegreen by signing an agreement to promote and build photovoltaic power generation projects incorporating Augwind’s AirBattery energy storage system.

Earlier this week, Augwind announced signing of an MOU with EDF Renewables Israel Ltd., a subsidiary of the global EDF conglomerate, one of the largest multinational electricity utility companies in the world. Under the terms of the agreement, Augwind and EDF will work together to build and operate a 5 MW photovoltaic power plant, with a 20 MWh AirBattery storage system. The project will be built with a secured PPA from the government-owned electricity company (IEC) for 23 years.

Augwind recently announced the results of the tests performed in the proof of technological feasibility stage for the AirBattery system’s efficiency, with a huge promise to the energy marketplace. The system’s overall efficiency in the context of commercial facilities, with a capacity above 5 MW, is expected to be in the range of approximately 75-81%, depending on the characteristics and the various requirements of each storage project and the storage system components it comprises. The assessed results signify an astonishing breakthrough in the field of Compressed Air energy storage, positioning Augwind’s solution as a natural advantageous contender with compare to alternative technologies for various energy storage applications.

According to Or Yogev, CEO and Founder of Augwind, «The data presented by Augwind today is excellent news for the world of renewable energies in general and the world of energy storage in particular, both in comparison with lithium batteries and alternative storage solutions. Augwind’s AirBattery system has an energy efficiency that is generally similar to pumped storage stations’ efficiency.

Compared to a storage system based on lithium batteries, despite their higher initial efficiency, lithium batteries have an obvious disadvantage in that their efficiency and structural capacity fade over the years and necessitate replacement and upgrade for a new storage system every few years or cycles. In addition, lithium-ion systems contain chemical components, some of which are not recyclable, while Augwind’s solution is designed for decades, while also being green, environmentally friendly, and based solely on water and air.»

The advantages of the AirBattery system compared with existing systems:

  • Completely green: AirBattery is a first-of-its-kind system, without any flammable or chemicals materials, producing energy solely from water and air.
  • A multi-use system that allows unlimited number of cycles with a lifetime fixed capacity and zero degradation.
  • A storage system with a decades-long life-span and low CAPEX and OPEX costs
  • A safe subterranean storage system with minimum footprint, that can be deployed underground functional areas.
  • A modular, highly scalable system, enabling a range of storage volumes from tens of megawatts-hour through hundreds of megawatts-hour at a competitive cost.

About Augwind:

Augwind was founded in 2012 by Or Yogev. The company specializes in the development and installation of compressed air storage systems to increase energy efficiency (AirSmart™) and for storing energy for the electricity sector and, among other things, doing so from renewable electricity generation sources such as PV or wind power, which include the storage system developed by Augwind (AirBattery™).

Augwind operates on two fronts: the energy storage market and the air compressor market. Both commercial verticals are based on Augwind’s patented, AirX™ technology, proprietary underground air compression method and system that enables savings of up to 40% in the energy consumption required to compress the air at high pressure. The company’s customers include local and global industries such as PepsiCo, Tnuva, Strauss, Iscar, Rapac, IAI, Nesher Cement Industries and many others, with proven track record for Augwind’s AirX core technology.

Link to Augwind’s website:  https://ir.aug-wind.com

Contact: Tamir Vieman
tamir@aug-wind.com


Cision View original content:http://www.prnewswire.com/news-releases/augwind-to-build-120-mwh-electricity-storage-systems-in-one-of-the-worlds-largest-energy-storage-tenders-301202784.html

SOURCE Augwind

ATRESERIES, primer canal de TV que estrena ‘Velvet Colección’ en las Américas

MADRID, 7 de enero de 2021 /PRNewswire-HISPANIC PR WIRE/ — Atreseries estrena a partir del 17 de enero las dos temporadas de ‘Velvet Colección’, el spin off de Movistar+ con el que se pone punto final a la serie original de Atresmedia y Bambú Producciones. De esta forma, Atreseries se convierte en el primer canal de televisión que ofrece ‘Velvet Colección’ en las Américas y lo hace, además, después de haber emitido consecutivamente las cuatro temporadas anteriores de ‘Velvet’.

<div…

MADRID, 7 de enero de 2021 /PRNewswire-HISPANIC PR WIRE/ — Atreseries estrena a partir del 17 de enero las dos temporadas de ‘Velvet Colección’, el spin off de Movistar+ con el que se pone punto final a la serie original de Atresmedia y Bambú Producciones. De esta forma, Atreseries se convierte en el primer canal de televisión que ofrece ‘Velvet Colección’ en las Américas y lo hace, además, después de haber emitido consecutivamente las cuatro temporadas anteriores de ‘Velvet’.

Velvet Colección

Con ‘Velvet Colección’ continúa la #velvetmania al canal y el éxito de las galerías de moda más populares de la televisión con gran parte del reparto original, encabezado por Marta Hazas, Javier Rey, Aitana Sánchez-Gijón, Adrián Lastra y Asier Etxeandía, a los que se suman las nuevas incorporaciones de Imanol Arias, Mónica Cruz (Un paso adelante), Megan Montaner (Sin identidad), Andrea Duro (Física y química) y Adriana Ozores (Gran hotel) y Paula Usero (#Luimelia)

El primero de los 20 capítulos de ‘Velvet Colección’ (20×50′) se sitúa a finales de los años sesenta, con Ana Ribera (Paula Echevarría) afincada en Nueva York junto a su marido (Miguel Ángel Silvestre) y su hijo. Han pasado cinco años en los que Ana ha liderado la compañía a distancia, y ahora toca volver a España para dar un paso más en su proyecto y seguir la estela de otras empresas internacionales. Ana tiene claro que el nuevo reto es lograr franquiciar la prestigiosa marca ‘Velvet’ y demostrar que es capaz de replicar el modelo. Barcelona será la ciudad elegida para inaugurar el segundo centro ‘Velvet’, donde todos sus amigos y compañeros serán los responsables de convertir su sueño en realidad. Pero lo que sin duda va a ser un nuevo éxito no va a estar exento de problemas desde el primer momento. El destino le tiene preparado a la diseñadora una dura prueba.

HORARIOS DE EMISIÓN
Todos los domingos, a partir del 17 de enero

Latinoamérica
20:00h México/21:00h Colombia/22:00h Venezuela/23:00h Argentina

EE. UU.
21:00h ET /18:00 PT

Dirección de Comunicación y Relaciones Públicas | @Atreseriesint | blanca.aguirre@atresmedia.com | +34 91 623  49 67 | www.atreseries.com

Foto – https://mma.prnewswire.com/media/1395089/VELVET_COLECCION.jpg

FUENTE Atresmedia Internacional